More than half of people in their 50s and early 60s who left their last job did so for involuntary reasons such as ill health, caring responsibilities or redundancy, putting retirement incomes at risk, according to analysis from the International Longevity Centre UK (ILC).
The ILC warned that pensions policy still largely assumed people will remain in work and continue saving until state pension age, despite many leaving the labour market years earlier and losing both earnings and pension contributions.
Its paper, Retirement transitions: Acting now to support better outcomes for those on the verge of retirement, estimated that around 1.1 million people aged 50 to 64 who had left their last job had done so involuntarily, with poor health accounting for 45 per cent of economic inactivity among this age group.
Employment rates also fall sharply through later working life, from around 82 per cent among those aged 50 to 54 to 58 per cent among 60 to 64-year-olds.
The ILC stressed that early labour market exit could significantly reduce retirement adequacy by cutting off earnings and pension contributions while people may begin drawing down retirement savings.
The research, produced as part of ILC’s work with the Standard Life Centre for the Future of Retirement, also highlighted the limited pension wealth held by many approaching retirement.
A quarter of 55 to 64-year-olds with private pensions not yet in payment have combined pension wealth of less than £30,000, while the median is £97,000.
Among defined contribution (DC) pension holders, median DC wealth stands at £45,000.
Around one in five people in this age group have no private pension wealth at all.
Meanwhile, gender disparities remained significant, with women aged 55 to 64 who hold private pension wealth having a median of £105,000, almost £90,000 less than men.
ILC noted that career breaks, caring responsibilities and the gender pay gap continued to compound retirement inequalities across working lives.
Housing costs were also identified as a growing pressure, with 28 per cent of 55 to 64-year-olds renting privately or through social housing and therefore likely to face ongoing housing costs in retirement.
ILC deputy chief executive, Ben Franklin, argued that pensions policy must "confront the reality" that many do not have a full work history and then retire at state pension age before receiving their pension.
“Millions are instead leaving the labour market early, increasingly with defined contribution pension pots that are being accessed well before pensionable age," he added.
Franklin highlighted the issue was particularly acute for women, who were more likely to have experienced time out of the workforce for childcare and later-life caring responsibilities.
“Decumulation pathways need to be flexible and adaptable enough to reflect the different realities people and households are facing on the verge of retirement,” he added.
The ILC called on the Pensions Commission to make the transition between work and retirement a central part of its final recommendations, alongside efforts to improve saving levels.
It said policy should focus on both supporting longer working lives and the “gap years” between involuntary labour market exit and state pension age, where existing policy frameworks currently have limited reach.
Standard Life Centre for the Future of Retirement director, Catherine Foot, warned the assumption that people work steadily until state pension age before drawing retirement income was “far from reality”.
“The path to retirement is less straightforward today compared to previous generations, with people reaching later life in different work situations, financial positions and with different responsibilities,” she continued.
“As the Pensions Commission considers ways to improve retirement adequacy, we need to ensure the years before state pension age are not overlooked.”

Latest News
-
Industry calls for 2028 ‘test year’ before VFM ratings go public
-
Developing future-proof pension systems in the near term ‘critical’ for retirement security
-
Over-50s forced out of work early face growing retirement income risk
-
Givaudan UK Pension Plan completes wind-up with benefits secured by Aviva
-
Special Melted Products scheme completes £52m buy-in with Canada Life
-
Western Pension Solutions joins Collective Pensions
Supporting retirement decisions
Laura Blows discusses retirement saving levels in the UK, and the support required for members, trustees and employers, with WEALTH at Work director, Jonathan Watts-Lay
Podcast: From pension pot to flexible income for life
Podcast: Who matters most in pensions?
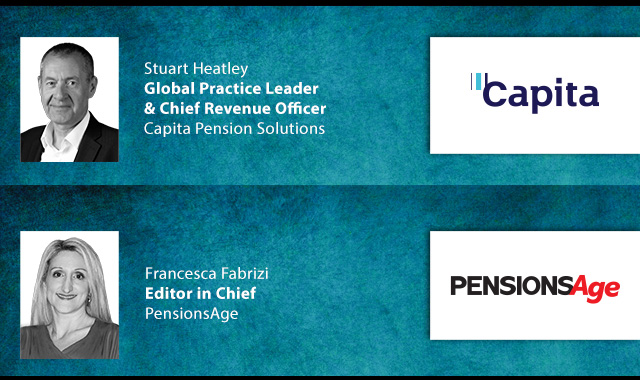
In the latest Pensions Age podcast, Francesca Fabrizi speaks to Capita Pension Solutions global practice leader & chief revenue officer, Stuart Heatley, about who matters most in pensions and how to best meet their needs
© 2019 Perspective Publishing Privacy & Cookies
Recent Stories